Low-capex DSO hematite in Brazil’s Iron Quadrangle (Minas Gerais), short-haul to Vale, Avante, and ArcelorMittal.
Supergene-enriched hematite at Florália. Weathering has leached silica from the banded iron formation and concentrated iron into a soft, friable, high-grade structure: the reason the ore can be mined free-dig and upgraded dry.
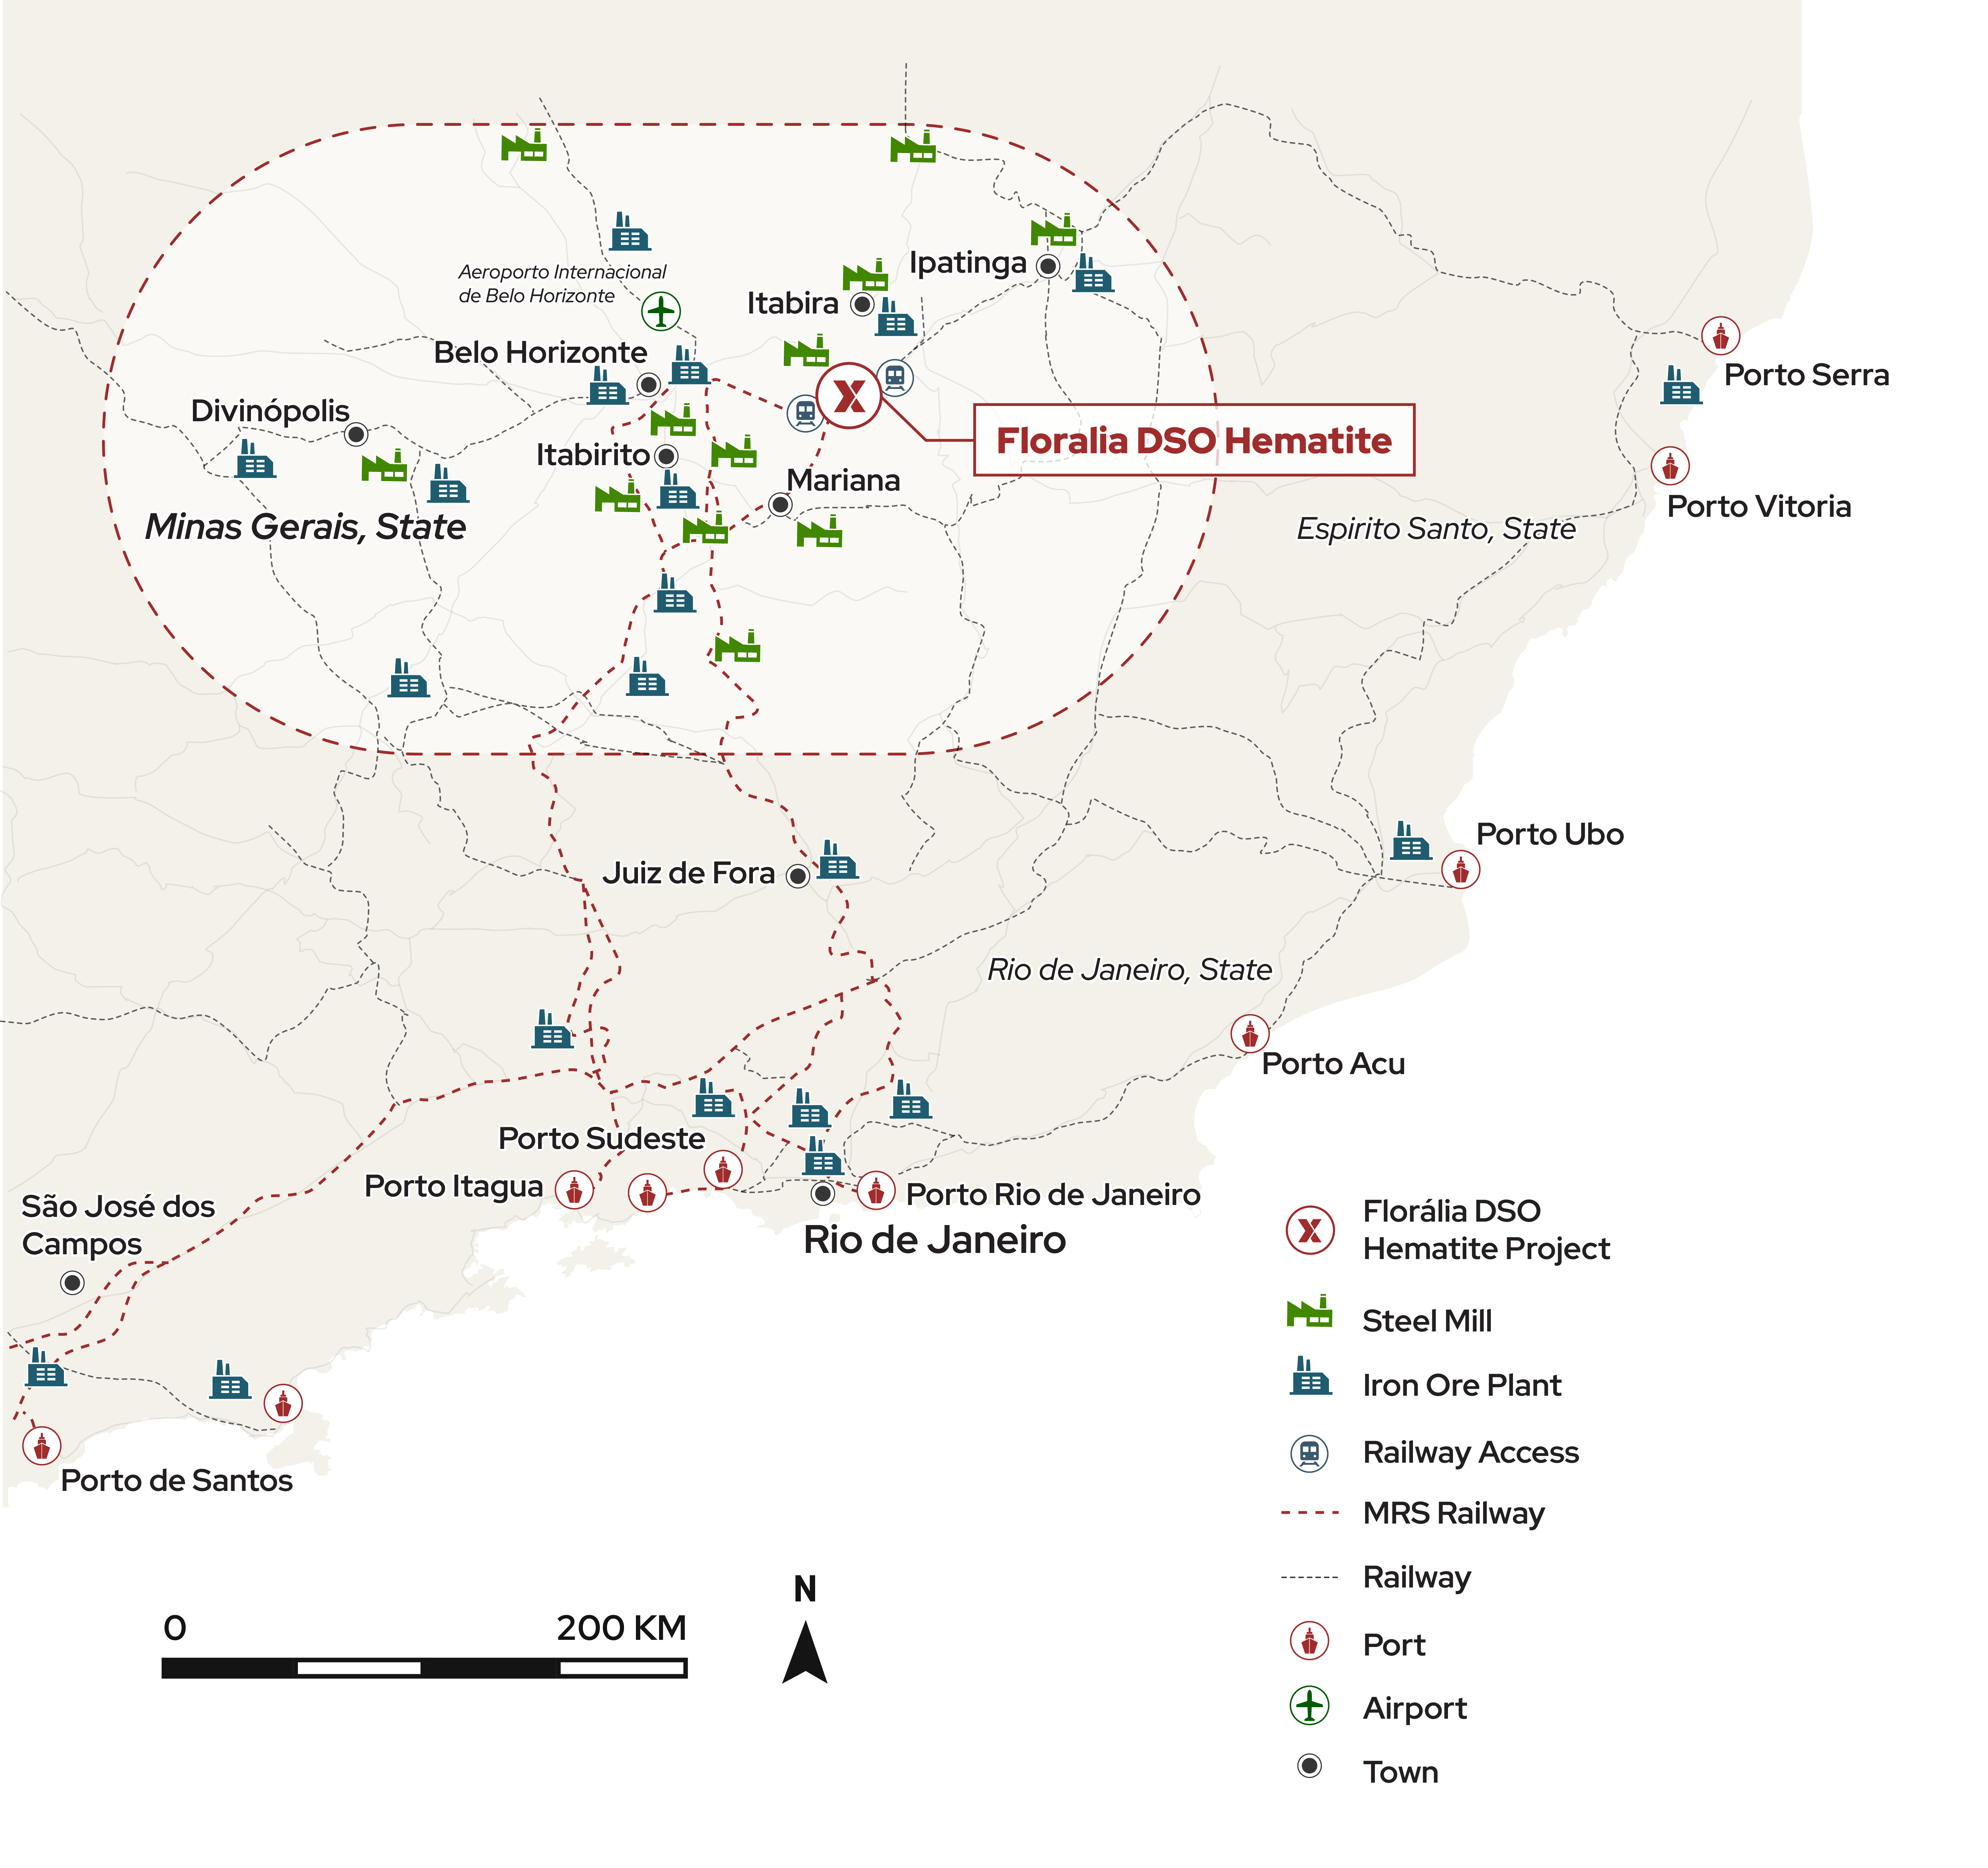
70 km east of Belo Horizonte, Minas Gerais. ~613 hectares surrounded by producing mines and steel mills, with multiple buyers within 34 to 47 km by road.
One of the world's largest producers
Local miner and historical buyer
Major domestic steelmaker
The buyers are already there. Minas Gerais holds 9 of Brazil's 31 steel mills and 43 pig iron plants producing ~75% of national pig iron, buying granular ore at 55-64% Fe today.9
No offtake agreement is in place and no counterparty is committed.
Readers are cautioned that the geology of nearby properties is not necessarily indicative of the geology of the Property.
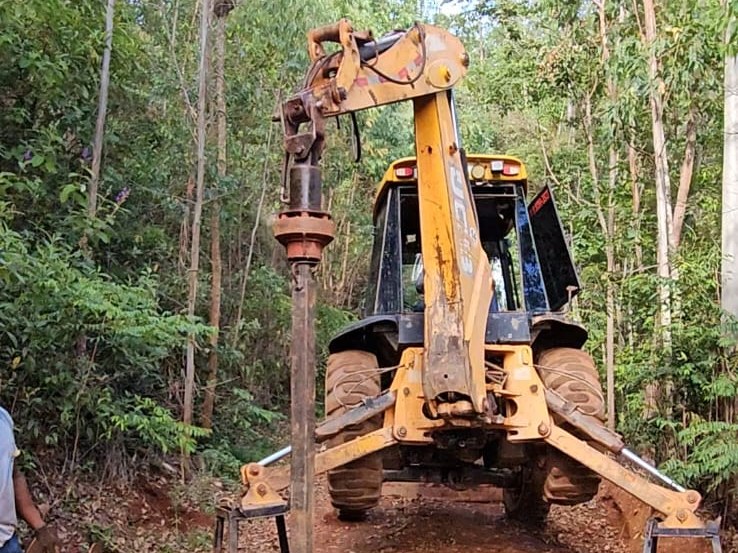
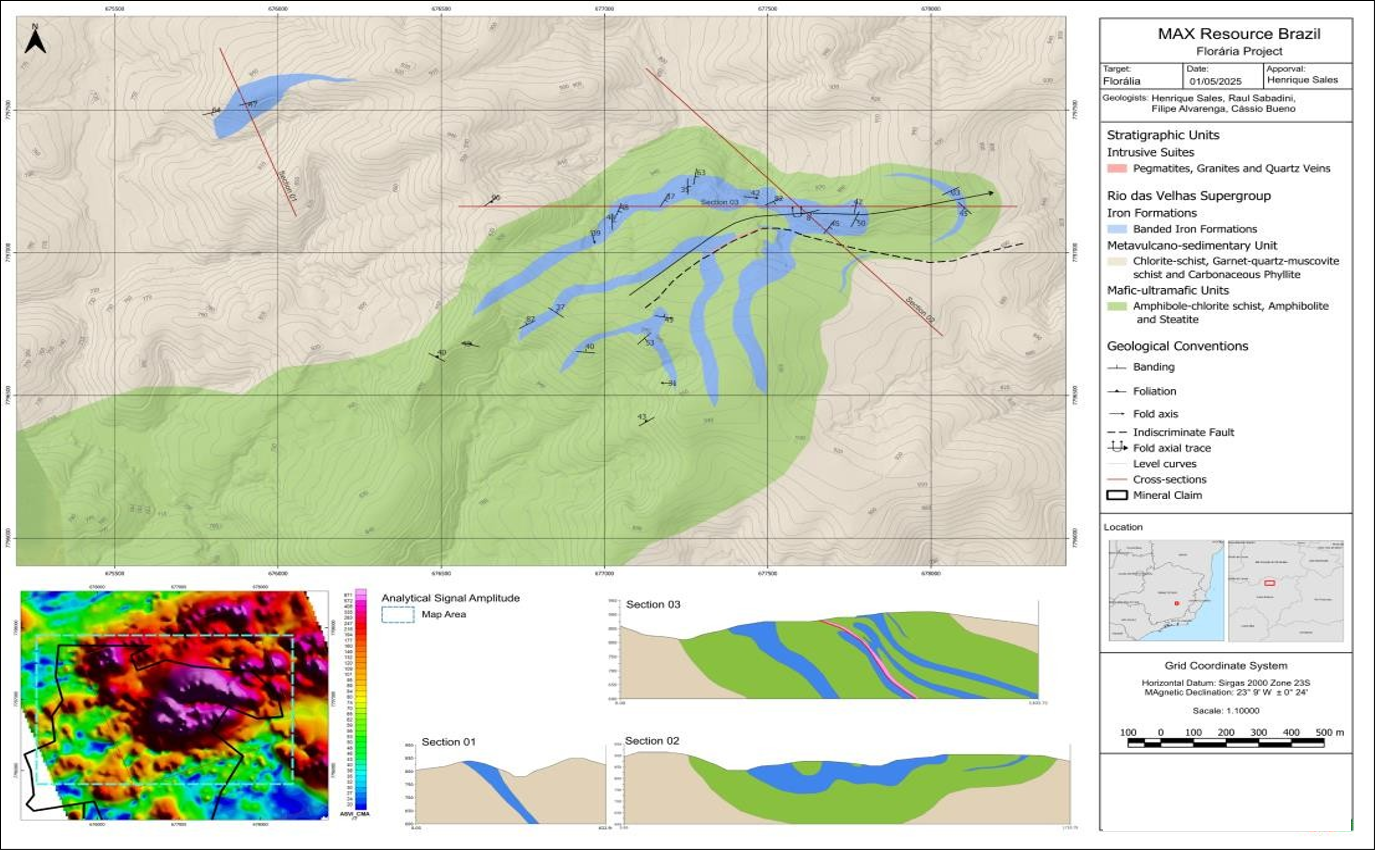
2024-2025 work program included airborne geophysics, geological mapping, geochemical sampling, diamond and auger drilling, and geometallurgical testing across the 613-hectare Florália claim area.

225 km of drone airborne LiDAR and magnetic survey. Identified mineralized zones and structural controls.
618 observation points. Detailed banded iron formation (BIF) lens definition across the entire claim area.
186 channel samples (Jaguar and Max). 68% returned grades above 50% Fe. Low phosphorus, 0.01-0.05%.
6 holes totaling 761m. Intersected 222m of oxidized iron formation.
86 holes (890m total), and 274 samples analyzed by SGS Geosol laboratory.
Six 80 kg bulk samples returned concentrates of 54-69% Fe depending on feed grade. Blended composites of ~47-52% Fe feed upgraded to 62-68% Fe, an 8 to 17 point increase, at ~60% mass recovery to a 61% Fe product.2,6 100% dry; no water and no tailings dam.

Free-dig mining, crush and screen, dry magnetic separation, biomass drying to ~3% moisture, 61% Fe sinter feed. No wet beneficiation.6
State environmental licensing (EIA/RIMA) in progress with SEMAD, the key path item. The CENIBRA surface indemnity (Acordo de Servidão) is being finalized to secure site intervention rights.
~US$12M conceptual: plant installation and acquisition ~US$6.0M, earthworks and site preparation US$2.0M, lab, equipment and machinery US$2.0M, working capital US$2.0M.7 Not supported by a feasibility study.
Target product 61.0% Fe, 3.0% SiO2, 1.3% Al2O3, 0.04% P: at the IODEX 61% benchmark on grade and below it on every penalty element.8 Blends well with lower-grade ore for nearby mills.
26 Metals Inc. management and technical advisors.
This team has already taken a high-grade hematite DSO project from the ground to a takeout. As CEO of Aztec Resources, technical advisor Brett Matich developed the Koolan Island hematite DSO project from a flooded open cut to operations (24.9 Mt at 65% Fe)5, through to its acquisition by Mt Gibson Iron in 2006.
Before 26 Metals, Mr. Kotowych held corporate development roles at junior miners, most recently at Abitibi Metals, advancing the B26 Polymetallic Deposit and Beschefer Gold Project. He conducted equity research on mining at Haywood and Red Cloud Securities. Exploration experience includes Great Bear (now Kinross), Carlisle (now Alamos), and Solstice Gold. Holds an MSc in Geophysics and Honours BSc in Math and Geology from the University of Toronto.
Dr. de Sales previously worked as an iron ore geologist with Vale and is fluent in English, Spanish, and Portuguese. He resides in Belo Horizonte, Minas Gerais. He has been responsible for developing hematite DSO mines in Brazil (1 to 3 Mtpa), including Ferro Puro, GSM and Corrego do Onca (all within 50 km of Florália).
Mr. Matich was CEO of Aztec Resources (ASX: AZR), which developed the Koolan Island Hematite DSO Project from a flooded open cut to operations (24.9 Mt at 65% Fe)5; AZR was acquired by Mt Gibson Iron (ASX: MGX) in 2006. As CEO of Cervantes (TSXV: CEV) he advanced the Block 103 prospect. He is currently CEO of Operations for the Sierra Azul Project in Colombia for Freeport.
Dr. Grainger has over 25 years of experience in South America with Newmont, Ivanhoe Electric (Friedland Group), Vale, Inco and Troy Resources. He was involved with Continental Gold's Buriticá project (acquired by Zijin in 2019) and co-founded Collective Mining. He is CEO of Helius Minerals (TSXV: HHH). He resides in Brazil and is fluent in Spanish and Portuguese.
Mr. Saltsman has 25 years of experience in venture capital and public investments and is the founder of First Lithium Minerals Corp., which he founded in 2017. He currently sits on the board of Leveljump Healthcare Corp. and has served as CEO of Compel Capital Inc. and RMM Ventures Inc., and as Vice President of Georgian Capital Corp. He is President and Managing Partner of Paige Capital Inc., a venture capital investment company, and a founding partner of South America Finance Corp SAS, a private merchant banking group in Colombia.
The Company is planning technical and economic studies on the Florália DSO project as exploration advances. Any feasibility-level study is contingent on first defining a mineral resource. A feasibility study and a construction decision are targeted for 2027, with first production targeted for the second half of 2027. These targets depend on exploration results, study outcomes, permitting, and financing.
No production decision has been made. Any development scenario is conceptual and subject to defining a mineral resource, study results, permitting and financing. Beyond Phase I, Florália's modular design offers a conceptual expansion path to up to 4.5 Mtpa with two additional lines and third-party rail and export logistics. This is optionality, not a committed plan: it is conditional on resource expansion, full EIA/RIMA permitting for the larger rate, long-term biomass supply contracts and self-funding from Phase I cash flow, and is not a basis for current valuation.
The project, the process, the route to market and the capital structure. Enter your email and the deck opens immediately.
By entering your email you consent to receive investor updates from 26 Metals Inc. Unsubscribe anytime. This is not an offer of securities or investment advice.
Focused on acquiring and developing high-grade hematite iron ore assets in Minas Gerais, Brazil.
info@twentysixmetals.com · 1245-300 Granville St., Vancouver, BC V6C 1V4, Canada
Sample grades are not a mineral resource and are not necessarily representative of the Property as a whole.
The exploration target referenced in the Company's disclosure was prepared by E. Cunha, MSc, AusIMM, for MAX Resource Corp. under the 2012 JORC Code and has not been prepared in accordance with NI 43-101 or current CIM Definition Standards for Mineral Resources and Mineral Reserves (2014). The Company's qualified person has reviewed the underlying data and methodology but has not independently verified or reclassified the exploration target under NI 43-101. No category under CIM Definition Standards has been assigned to the exploration target. An exploration target is conceptual in nature and there has been insufficient exploration to define a mineral resource; there is no guarantee that further exploration will result in the delineation of a mineral resource. Significant data compilation, re-drilling, re-sampling, and data verification may be required before the exploration target can be verified and classified as a current mineral resource under NI 43-101. There can be no assurance that any portion of the exploration target will ever be confirmed or become economically viable. Readers are cautioned not to place undue reliance on this exploration target.
The scientific and technical disclosure on this website has been reviewed and approved by Deepak Varshney, P.Geo., a Qualified Person as defined under NI 43-101.
No offtake agreement is in place and no counterparty is committed. 26 Metals has not entered into and is not negotiating any transaction, offtake or otherwise, with Vale or any other party, and has had no discussions with Vale. References to nearby operators and buyers are market context only and do not imply any value for the Florália project.
Any referenced metallurgical test results, drilling, or other technical data from previous operators are considered historical in nature. A Qualified Person has not done sufficient work to verify this information, and readers are cautioned not to place undue reliance on these historical results.
Readers are cautioned that the geology of nearby properties is not necessarily indicative of the geology of the Property.
The comparison of the magnetite route and the Florália direct shipping ore approach describes general process characteristics of the two processing routes. It is not a comparison of specific projects and is not based on a study of either route. The Florália initial capital figure is a conceptual estimate prepared by the Company and is not supported by a feasibility study; the Phase I rate is a regulatory cap, not a forecast; and the production target is forward-looking information subject to a mineral resource, study results, licensing and financing. The Florália processing approach is conceptual and no production decision has been made.